Selling to customers in Bangladesh but don’t have an office here? Then Bangladesh’s VAT law probably expects you to appoint a VAT agent: a qualified local person who registers, files and pays VAT on your behalf.
Get it right and VAT runs quietly in the background. Get it wrong, and fines, interest and blocked payments can follow.
This guide explains, in plain English, who needs a VAT agent in Bangladesh, who can be one, and exactly how to appoint one.
Key takeaways
- A foreign business with no fixed place of business in Bangladesh must appoint a VAT agent (Section 19, VAT and Supplementary Duty Act 2012).
- Your VAT registration is in your name, not the agent’s. The agent operates it for you.
- Only certain people can be agents, including lawyers enrolled with the Bangladesh Bar Council and chartered or cost accountants.
- The agent shares legal liability with you for unpaid VAT, fines and interest.
- Standard VAT is 15%. Returns are filed quarterly and online, within 15 days after each quarter ends.
In this guide: What is a VAT agent? · Who needs one? · Who can be one? · How to appoint one · Agent vs consultant · Business vs consumer sales · Key numbers · Penalties · FAQs
What is a VAT agent?
A VAT agent is a qualified person in Bangladesh who handles VAT for a foreign business that has no office or fixed place of business here. In Bangla, the role is called ভ্যাট এজেন্ট.
Think of them as your VAT representative on the ground. They register you with the National Board of Revenue (NBR), file your returns, pay the VAT you owe, and answer the NBR’s questions.
The rule comes from Section 19 of the Value Added Tax and Supplementary Duty Act, 2012. It says a non-resident with no fixed place of business in Bangladesh shall appoint a VAT agent. It’s a legal requirement, not an optional extra.
Good to know: your VAT registration (your BIN) is issued in your business’s name. Section 19(3) says registration through a VAT agent is “in the name of the principal”.
Who needs a VAT agent in Bangladesh?
You need a VAT agent if the answer to both of these questions is yes:
- Is your business non-resident? It isn’t incorporated in Bangladesh and isn’t managed from here.
- Do you have no fixed place of business in Bangladesh? No branch, no liaison office, no local company.
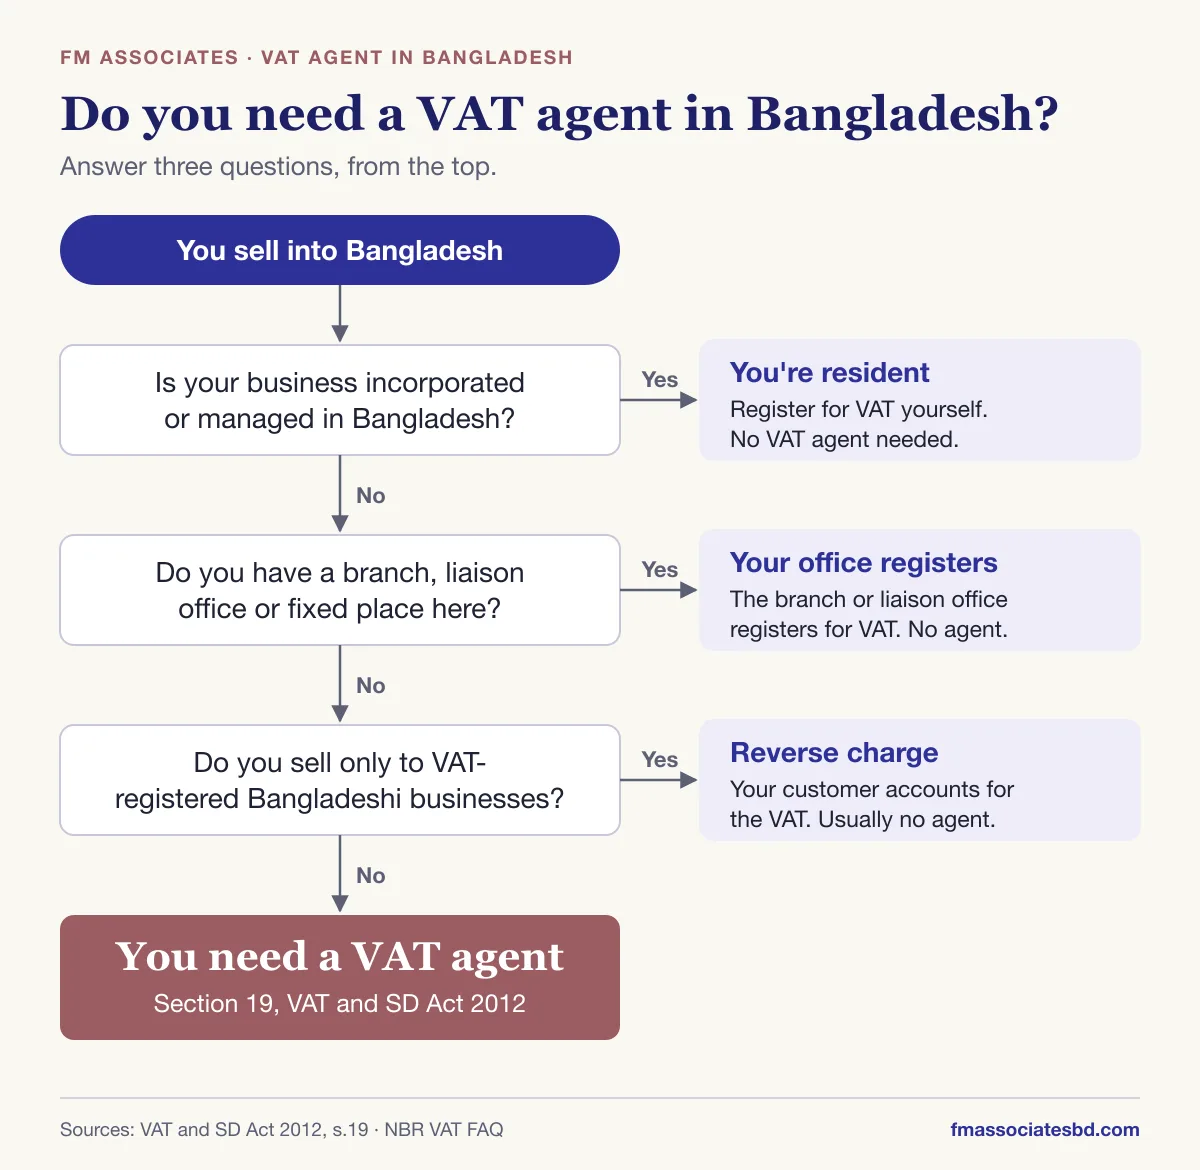
Here’s how that plays out in common situations:
| Your situation | Need a VAT agent? |
|---|---|
| Foreign app, SaaS, streaming or online-ads business selling to people in Bangladesh | Yes, in most cases |
| Foreign business selling services only to VAT-registered Bangladeshi companies | Usually no. Your customer pays the VAT through the reverse charge (see below) |
| Foreign company with a branch or liaison office in Bangladesh | No. The office registers for VAT itself. See how to set up a branch office or open a liaison office |
| Bangladeshi subsidiary of a foreign group | No. It’s a resident company. See how to incorporate a company in Bangladesh |
| Foreign contractor making taxable supplies in Bangladesh with no local office | Usually yes |
Not sure which applies to you? A short call with a VAT adviser usually settles it.
What “non-resident” means
Under Section 2(15) of the Act, a company is resident if it’s incorporated in Bangladesh (with the Registrar of Joint Stock Companies) or controlled and managed from here. Anything else is non-resident.
An individual is resident if they normally live in Bangladesh, or stay here:
- more than 182 days in the current calendar year, or
- more than 90 days this year and more than 365 days in total over the previous four years.
Who can be a VAT agent?
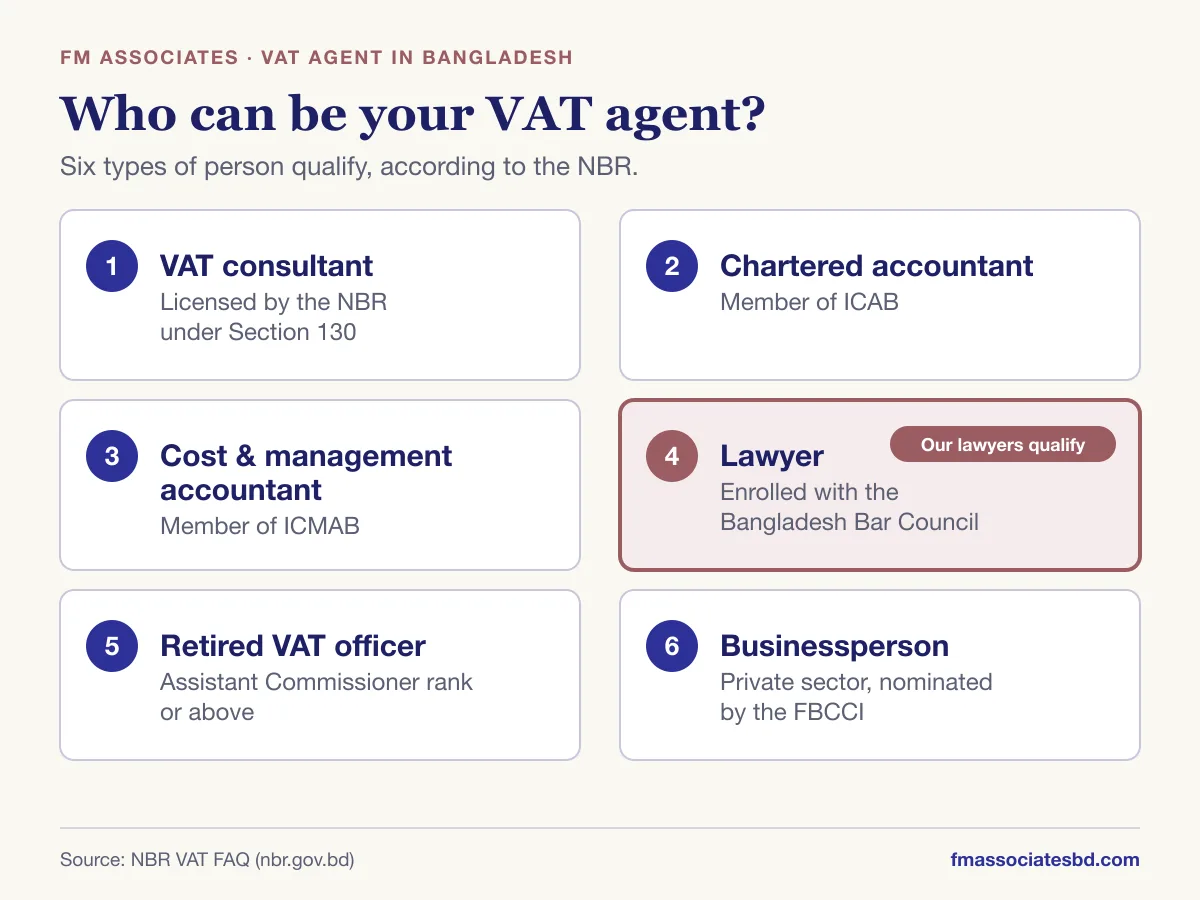
Not just anyone. According to the NBR’s VAT FAQ, your VAT agent must be one of these:
- A VAT consultant licensed by the NBR under Section 130 of the Act
- A member of the Institute of Chartered Accountants of Bangladesh (ICAB)
- A member of the Institute of Cost and Management Accountants of Bangladesh (ICMAB)
- A lawyer enrolled with the Bangladesh Bar Council
- A retired VAT officer of Assistant Commissioner rank or above
- A private-sector businessperson nominated by the FBCCI
How to appoint a VAT agent in 4 steps
Appointing an agent happens mostly online, and it’s quick once your paperwork is ready.
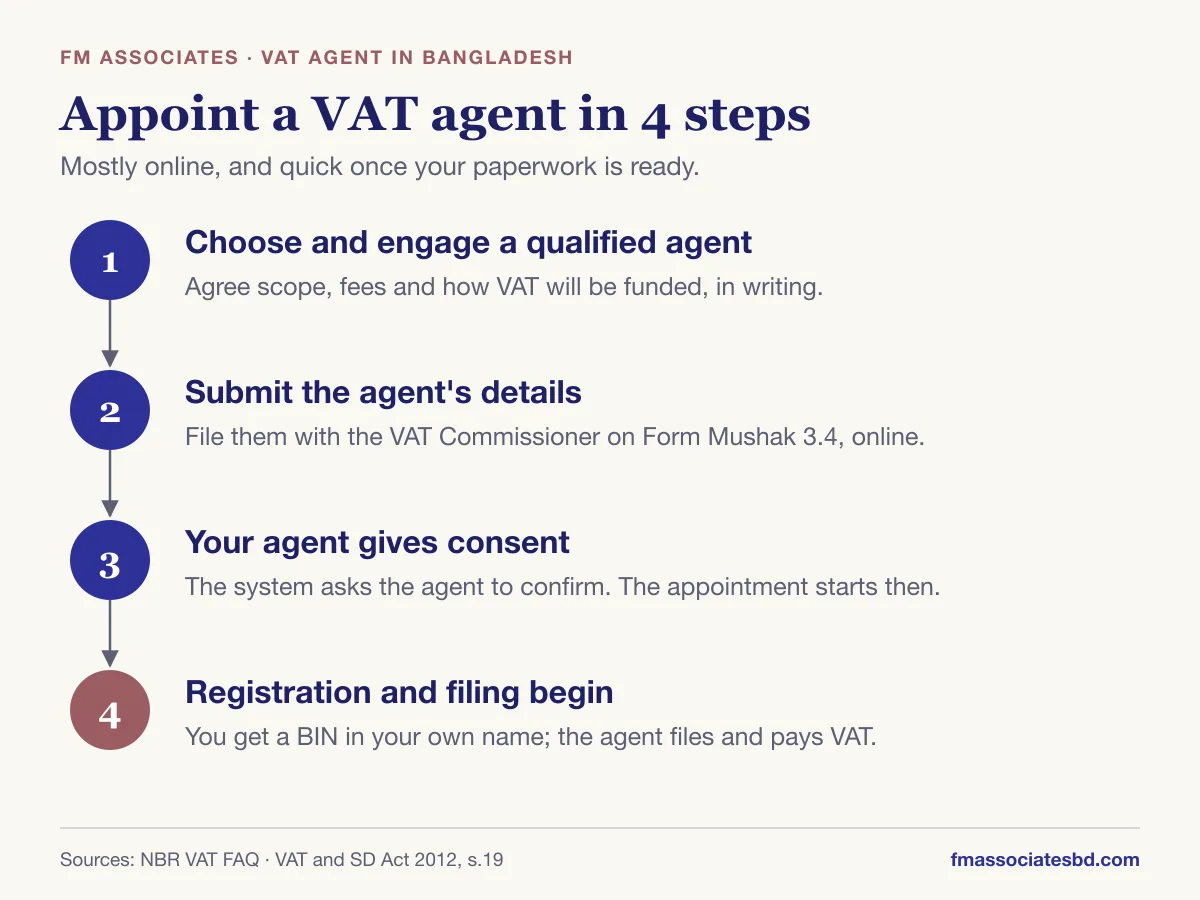
- Choose a qualified agent and agree terms. Sign an engagement letter covering scope, fees, how VAT money will be funded, and who handles NBR notices.
- Submit the agent’s details to the VAT Commissioner. The NBR says this is done on Form Mushak 3.4, through the online VAT system.
- The agent gives consent. The system asks your agent to confirm. The appointment takes effect once they consent.
- The agent registers your business and starts filing. You get a VAT registration (BIN) in your business’s name, and the agent files and pays from then on.
What your agent will usually ask you for:
- your company’s registration documents and registered address
- what you sell to Bangladesh, and to whom (businesses or consumers)
- a contact person who can approve filings
- how VAT will be funded, for example payments from your overseas account, which Grant Thornton notes is possible
The exact list varies, so your agent will confirm it.
What does a VAT agent do for you?
A good VAT agent handles your whole VAT cycle in Bangladesh:
- Registration: getting your BIN in your business’s name
- Returns: filing your VAT return (Form Mushak 9.1) online, on time
- Payment: depositing the VAT you owe by the deadline
- Records: keeping the records the law requires
- NBR contact: answering letters, queries and audits
- Changes: updating or closing your registration when your business changes
Under Section 19(2), the agent “shall bear all responsibilities” and carry out the VAT activities of the business they represent.
Is the VAT agent liable for your VAT?
Yes, the agent shares the risk. Section 19(2) makes the agent jointly and severally liable for taxes, fines, penalties and interest.
In plain English: if VAT goes unpaid, the NBR can collect the full amount from either you or your agent.
That’s why a serious agent will want clear terms on how VAT is funded and paid on time. It protects you both.
VAT agent vs VAT consultant: what’s the difference?
The two roles overlap, but they aren’t the same thing.
| Topic | VAT agent | VAT consultant |
|---|---|---|
| Legal basis | Section 19 of the Act | Section 130 of the Act |
| Who appoints them | A non-resident business with no fixed place in Bangladesh | Any taxpayer who wants advice or representation |
| What they do | Carry out all of the business’s VAT obligations | Advise the taxpayer and represent them before VAT officials |
| Liable for your VAT? | Yes, jointly and severally | Not by being a consultant |
A licensed VAT consultant is one of the six types of person who can become your VAT agent. Once appointed as agent, they take on the agent’s duties and liability.
Business customers vs consumers: who pays the VAT?
It depends on who your customer is.
| Question | Selling to Bangladeshi businesses (VAT-registered) | Selling to Bangladeshi consumers (not registered) |
|---|---|---|
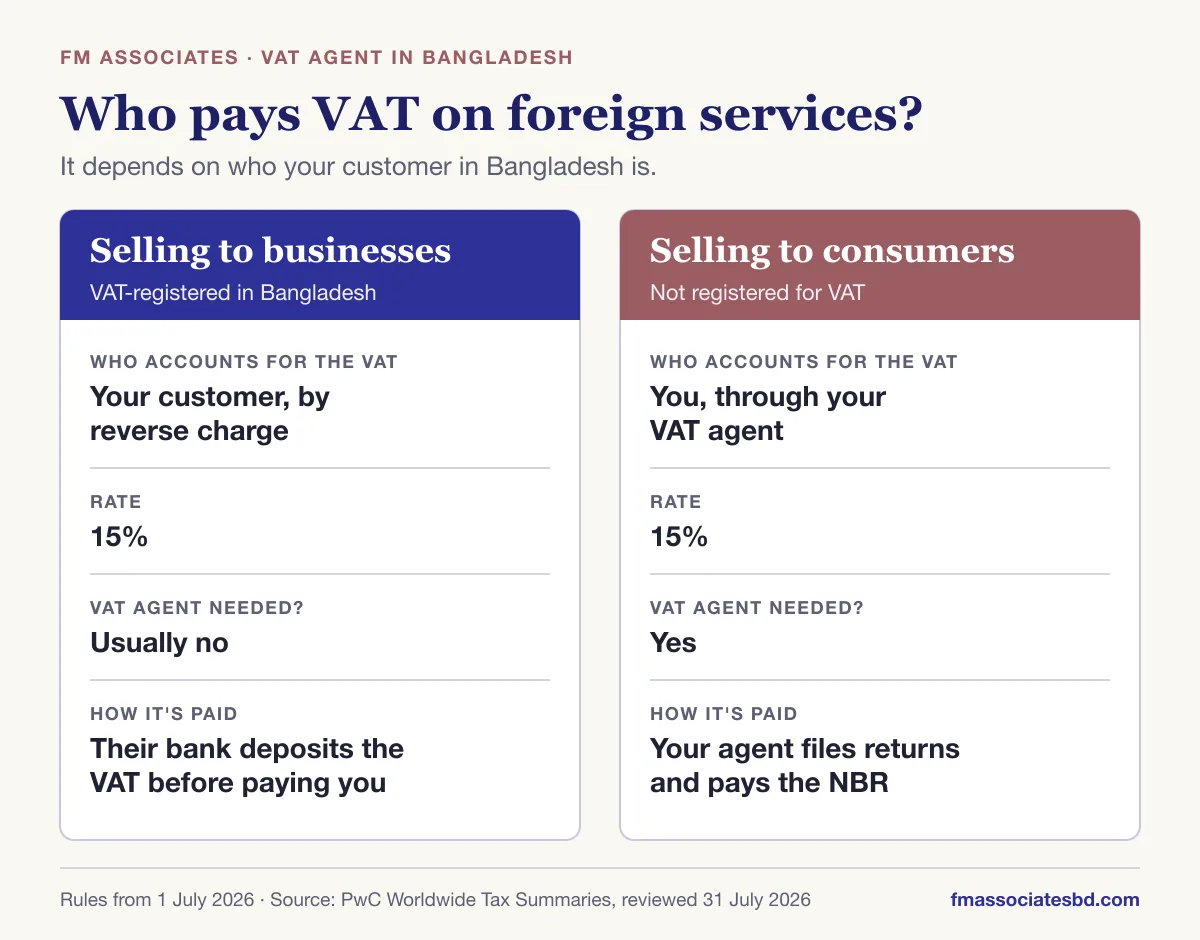
| Who accounts for the VAT? | Your customer, through the reverse charge | You, through your VAT agent |
| Rate | 15% | 15% |
| Need a VAT agent? | Usually no | Yes |
| How it’s paid | The customer’s bank deposits the VAT before sending your payment abroad | Your agent files returns and pays the NBR |
From 1 July 2026, most imported services are taxed at 15% under the reverse charge. The bank sending the payment abroad must deposit that VAT first (PwC); payments abroad also follow Bangladesh Bank rules.
This follows the international norm. The OECD’s International VAT/GST Guidelines recommend taxing cross-border services where the customer is.
Key VAT numbers for 2026-27
| What | The number |
|---|---|
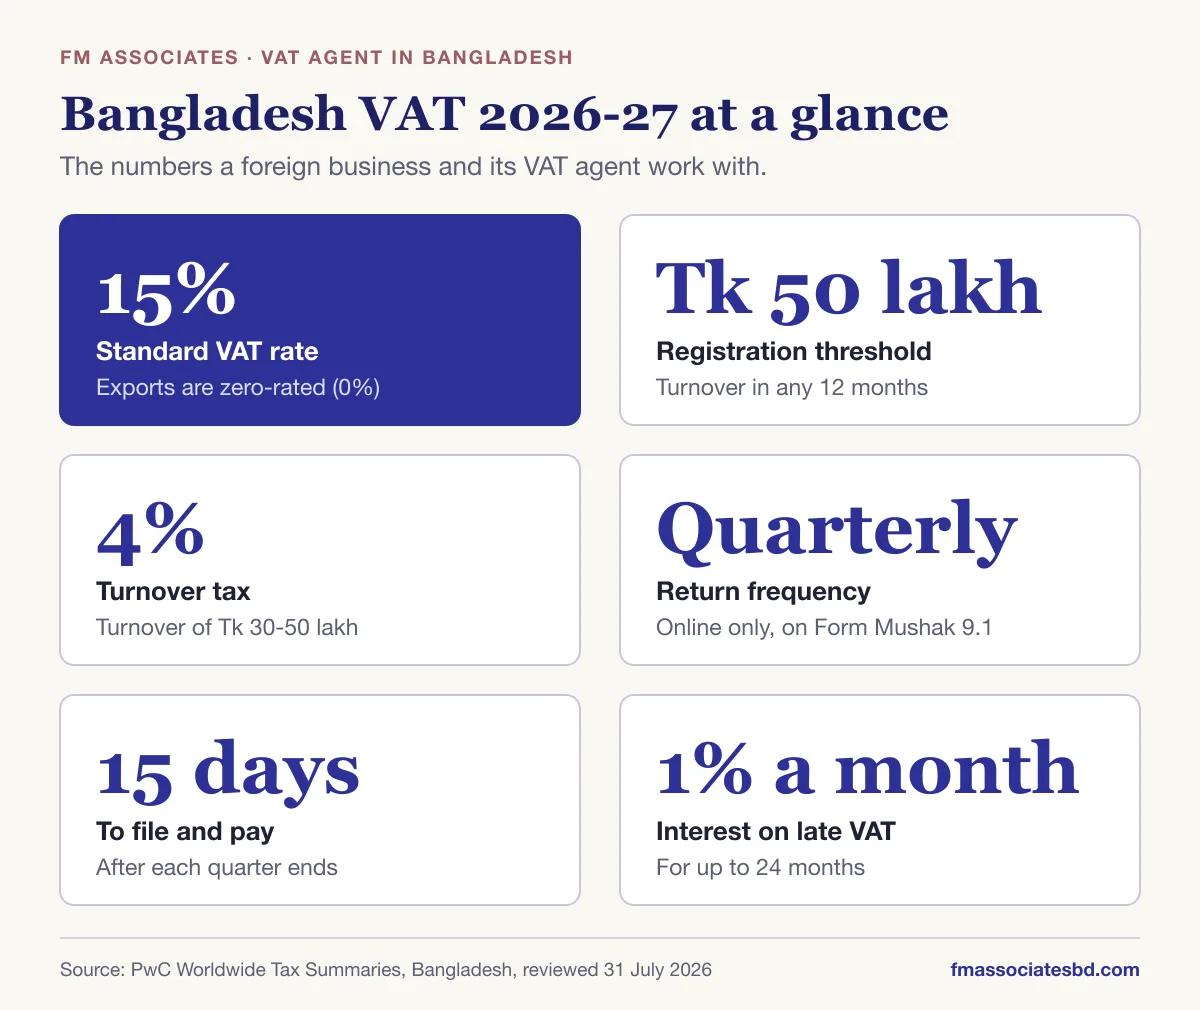
| Standard VAT rate | 15% |
| Exports | 0% (zero-rated) |
| VAT registration threshold | Turnover over Tk 50 lakh (Tk 5 million) in 12 months |
| Turnover tax (small businesses) | 4% for turnover between Tk 30 lakh and Tk 50 lakh |
| Return frequency | Quarterly by default; monthly is optional |
| Return deadline | Within 15 days after the quarter ends |
| How to file | Online only; manual filing ended on 1 July 2026 |
| Interest on late VAT | 1% per month, for up to 24 months |
Source: PwC Worldwide Tax Summaries, Bangladesh, reviewed 31 July 2026. Budget documents are published by the Ministry of Finance.
Some businesses must register whatever their turnover. These include importers, exporters, tender suppliers, and branch or liaison offices of foreign companies. If you’re a foreign digital business selling to consumers, don’t assume the Tk 50 lakh threshold protects you; ask your agent.
VAT registration also matters for banking. From FY2026-27, a VAT registration is needed to open a business bank account (The Daily Star). See how to open a bank account.
What happens if you don’t comply?
Missed VAT obligations cost money fast:
- Fines for not registering or not filing on time (Section 85 sets fixed amounts for these)
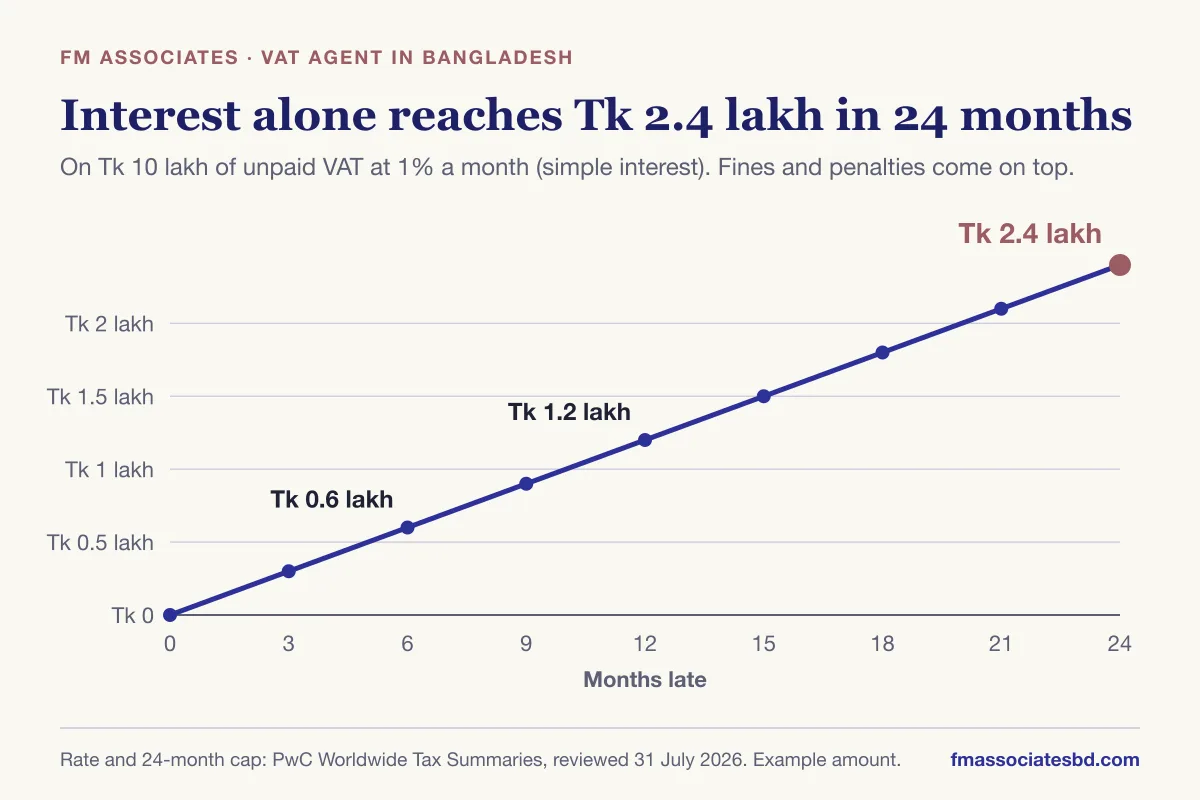
- Interest of 1% per month on late VAT, for up to 24 months
- Penalties of 30% to 50% for wrongly claimed or adjusted VAT credits (PwC)
- Up to twice the tax where VAT is deliberately evaded
On Tk 10 lakh of unpaid VAT, interest alone reaches Tk 2,40,000 after 24 months.
How to choose a VAT agent
Use this quick checklist:
- Legally qualified: one of the six categories above
- Files online confidently on the NBR’s VAT system
- Replies fast and writes clearly in English
- Clear, fixed fees, with no surprises
- Written terms on liability and how VAT is funded
- Audit experience, for when the NBR asks questions
- Keeps your data safe and your records in order
The ICAB’s VAT compliance manual is a useful reference if your finance team wants more detail.
How FM Associates can help
FM Associates advises foreign and local businesses on tax and VAT in Bangladesh. Our lawyers are enrolled with the Bangladesh Bar Council, which qualifies them to act as VAT agents. Our tax team includes AHM Belal Chowdhury, who has advised corporate clients on tax and VAT for over a decade.
We can:
- confirm whether you need a VAT agent
- act as your VAT agent and register your business
- file your returns and pay VAT on time
- handle NBR queries and audits
- help with your TIN certificate and wider tax and VAT legal services
Talk to our VAT team about appointing a VAT agent
Frequently asked questions
Who needs a VAT agent in Bangladesh?
A non-resident business with no fixed place of business in Bangladesh that makes taxable supplies here must appoint one, under Section 19 of the VAT and Supplementary Duty Act 2012. This is common for foreign digital, SaaS and streaming businesses selling to consumers.
Who can be a VAT agent in Bangladesh?
According to the NBR, an NBR-licensed VAT consultant, a member of ICAB or ICMAB, a lawyer enrolled with the Bangladesh Bar Council, a retired VAT officer of Assistant Commissioner rank or above, or a private-sector businessperson nominated by the FBCCI.
Is the VAT agent liable for my VAT?
Yes. Section 19 of the VAT and SD Act 2012 makes the agent jointly and severally liable with you for VAT, fines, penalties and interest, so the NBR can recover unpaid amounts from either of you.
Is the VAT registration in my name or the agent's name?
In your name. Section 19(3) says VAT registration through a VAT agent is in the name of the principal, which means your business.
Do I need a VAT agent if I have a branch or liaison office in Bangladesh?
No. A branch or liaison office is a fixed place of business, so it registers for VAT itself.
Which form is used to appoint a VAT agent?
According to the NBR, the agent's details are submitted to the VAT Commissioner on Form Mushak 3.4. The appointment takes effect once the agent consents in the online VAT system.
How often does a VAT agent file returns?
Quarterly by default, within 15 days after each quarter ends, on Form Mushak 9.1. Monthly filing is also allowed. Returns must be filed online.
Do I need a Bangladeshi bank account to appoint a VAT agent?
Generally no. A foreign supplier of electronic services can register through a VAT agent without a local office or a Bangladeshi bank account.
How much does a VAT agent cost in Bangladesh?
Fees depend on how often you file and how many transactions you have. Ask any agent for a fixed written quote that covers registration, each return and any NBR queries.
Sources
- The Value Added Tax and Supplementary Duty Act, 2012 (English text, National Board of Revenue)
- The Value Added Tax and Supplementary Duty Act, 2012, consolidated text (bdlaws.minlaw.gov.bd)
- National Board of Revenue, VAT FAQ
- PwC Worldwide Tax Summaries: Bangladesh, Corporate, Other taxes (reviewed 31 July 2026)
- Grant Thornton, Indirect tax guide: Bangladesh
- OECD, International VAT/GST Guidelines
- ICAB, Tax Planning and Compliance Manual (Indirect Tax, VAT portion)
- The Daily Star, budget FY2026-27: relief for low-income groups and businesses (12 June 2026)
This guide is general information, not legal advice. Laws and rates change; the figures here are current as of 31 October 2026. Speak to an adviser about your situation.